All Categories
Featured
In connection with its review of the UK listing program explained above, the FCA made a couple of modifications to the continuing commitments of noted companies, all of which ended up being efficient on 29 July 2024 with the adoption of the UKLR sourcebook. In connection with the collapse of the previous premium and basic listing sectors into the brand-new business business category, the Listing Concepts (set out in UKLR 2) were simplified to need commercial companies to: develop and preserve sufficient treatments, systems and controls to allow them to adhere to their commitments under the UKLR (Concept 1); deal with the FCA in an open and co-operative manner (Concept 2); take sensible steps to allow its directors to comprehend their duties and commitments as directors (Concept 3); show integrity towards the holders and prospective holders of its listed securities (Concept 4); guarantee that it deals with all holders of the very same class of its listed securities that remain in the same position equally in regard of the rights connecting to those noted securities (Principle 5); andcommunicate info to holders and prospective holders of its listed securities in such a way as to prevent the development or extension of a false market in those noted securities (Principle 6).
As part of the consultation on changes to the UK listing routine, the choice was taken to keep the role of sponsor. However, because of the lighter-touch regulation of the brand-new industrial business category (notably a relaxation of shareholder approval requirements for considerable and associated party deals as explained below), a sponsor is now only required to be designated: in the context on an IPO, where a business is seeking admission for the very first time; in the context of a significant or associated party deal, where a demand is made to the FCA for private assistance or modification or waiver of the guidelines in UKLR 7 or UKLR 8; in the context of a related celebration deal, to verify the deal is "fair and sensible"; in the context of a reverse takeover, to provide assistance and send a circular and prospectus; where required by the FCA due to a breach (or presumed breach) of the UKLR or DTR sourcebooks; for specific transfers between listing categories; andin the context of more share issuances, if a listed business is required to submit a file such as a prospectus to the FCA for approval.

Appropriately, under UKLR 7, commercial companies are needed to make a market statement as soon as possible after the terms of a substantial transaction (25%+ on any among the class tests (consideration, assets and capital), excluding transactions in the ordinary course of business) are concurred. No announcement requirements are prescribed for deals below that threshold, however the requirements of the UK Market Abuse Guideline (UK MAR) apply.
In the case of a disposal, the announcement must also consist of particular financial info. There is also an overarching catch-all responsibility to disclose any other relevant circumstances or information required to allow shareholders to evaluate the terms and effect of the deal. No investor approval or circular requirements use to a significant deal, nor exists any requirement to select a sponsor (save where assistance, waiver or adjustments from the FCA are looked for).
Can Digital Innovation Accelerate UK ROI?
Under UKLR 7.5, reverse takeovers (100%+ on any among the class tests (factor to consider, possessions and capital)) continue to require a market announcement, an FCA-approved circular and shareholder approval. Sponsor assistance should be obtained if a business is proposing to participate in a deal which might amount to a reverse takeover and one must be appointed in regard of the circular and any re-admission prospectus.
Appropriately, under UKLR 8, for transactions involving a related party (for instance, a 20% investor or current/former director) which exceed the 5% class test threshold (excluding transactions in the normal course of organization), the following requirements apply: board approval of the transaction, leaving out any conflicted directors; composed verification from a sponsor that the transaction terms are "fair and reasonable"; anda market statement as quickly as possible after the deal terms are agreed which must consist of, amongst other requirements, a "fair and sensible" statement by the board.
Attracting Venture Funding in UK Capital Markets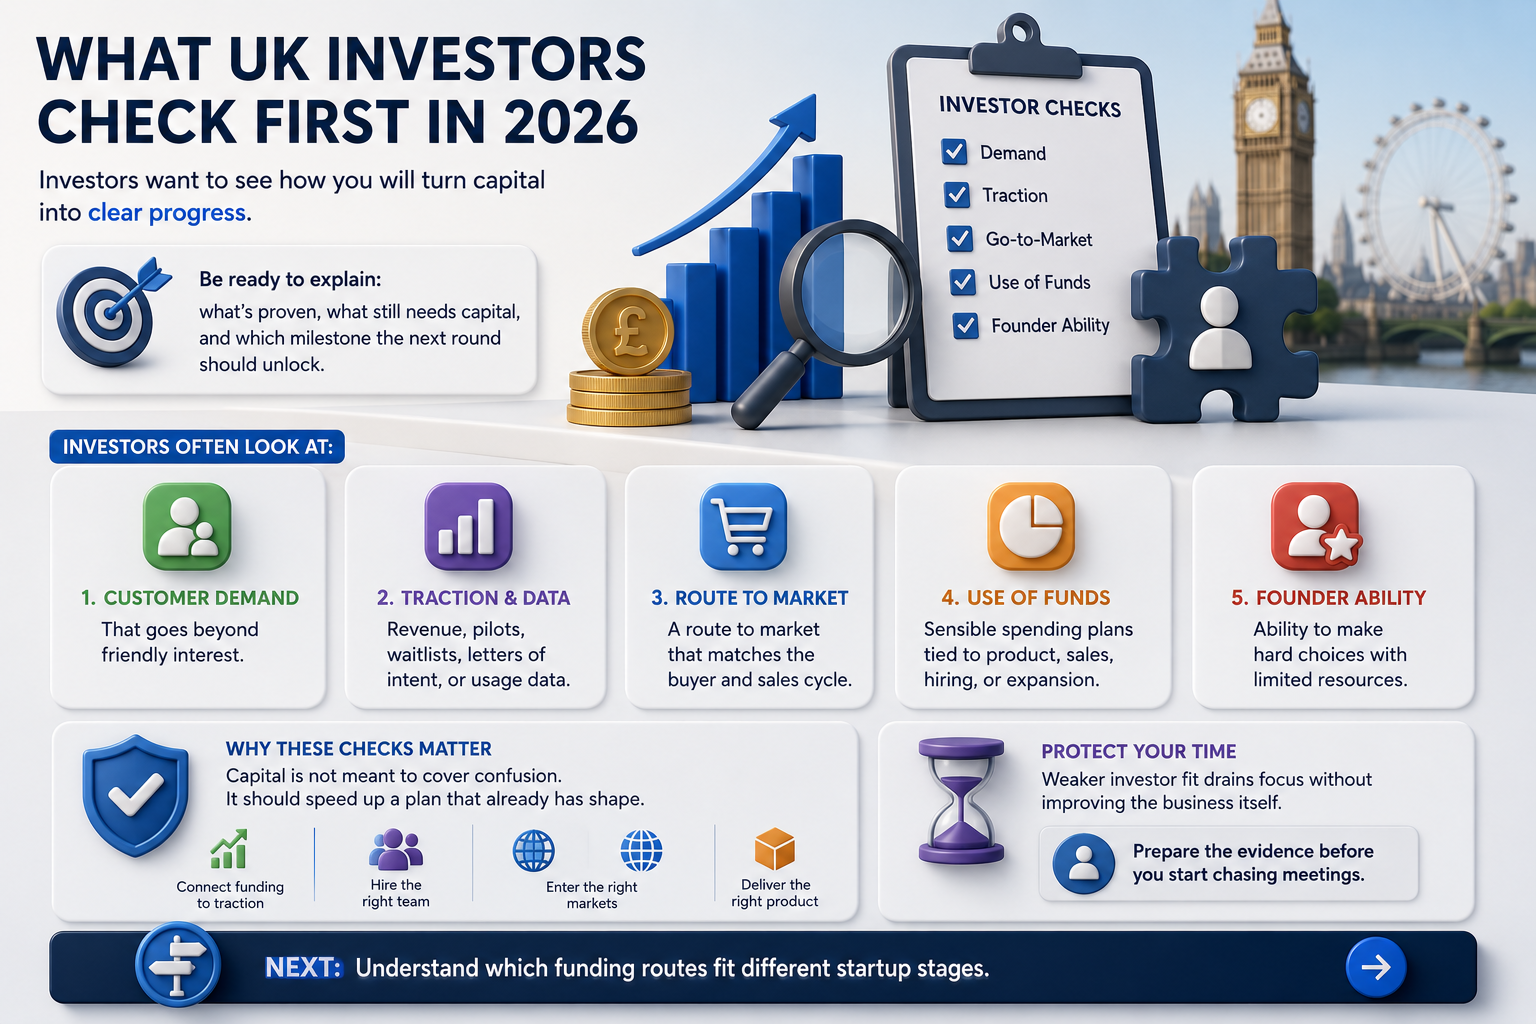
The findings of the review were released in July 2022 and consisted of several recommendations to the federal government, the FCA and the Pre-Emption Group (PEG).

Latest Posts
How Ethical Value Chains Drive UK Business Success
The Role of Sustainable Investment in UK Business Strategy
Smart Tactics to Guide 2026 Mid-Market Growth